How it works · Indexed Universal Life (IUL)
Growth potential with a built-in floor.
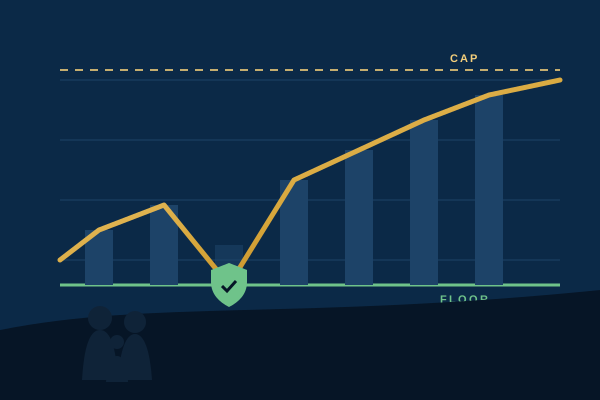
Indexed universal life is a type of universal life policy where cash-value interest is linked in part to the performance of a market index, such as the S&P 500®. Your money is not invested directly in the market, and policies typically include a floor that protects credited interest from going below a set rate — often 0%.
Coverage lengthPermanent, if funded
Cash valueIndex-linked
ProtectionFloor & cap
How it works
- When the index rises, your cash value is credited interest up to a cap or participation rate set by the carrier.
- When the index falls, the floor means credited interest does not go negative, though policy charges still apply.
- Like other UL policies, premiums and death benefit may be adjusted within policy limits.
- Cash value may be accessed through policy loans or withdrawals, which can reduce the death benefit.
Often a good fit for
- People seeking permanent coverage with cash-value growth potential
- Those comfortable with a more complex policy structure
- Families building a long-term, supplemental financial strategy
- Business owners exploring executive benefit planning
Things to consider
Caps, participation rates, and fees can change and limit returns. Illustrations are not guarantees. IUL policies need to be properly funded and reviewed regularly.