Independent life insurance broker · Free, no-obligation quotesCall or text: 586-368-7685
Life Insurance

Coverage for every chapter of life.

Every family is different, and so is every policy. Below is an in-depth look at the life insurance solutions GMGSJ helps clients understand and compare — how each one works, who it tends to fit, and what to consider before you decide.

Illustration representing Term Life Insurance
Term Life Insurance

Protection for the years that matter most.

Term life insurance provides a death benefit for a set period — commonly 10, 15, 20, or 30 years. If the insured person passes away during the term, the policy pays a tax-advantaged benefit to the beneficiaries they chose. If the term ends and the policy is not renewed or converted, coverage stops.

Coverage length10–30 year terms
Cash valueNone
Typical costLowest per dollar of coverage

How it works

  • You choose a coverage amount and a term length that matches a specific need, such as raising children or paying off a loan.
  • Premiums are often level (they stay the same) for the full term.
  • Many policies offer a conversion option that lets you switch to permanent coverage later without a new medical exam, subject to policy terms.
  • Some carriers offer optional riders, such as accelerated benefits for terminal illness or a child term rider.

Often a good fit for

  • Young families who want the most coverage for their budget
  • Homeowners protecting a mortgage balance
  • Parents who want to replace income until children are grown
  • Business owners covering a loan or partnership agreement
Things to consider

Term life does not build cash value, and premiums to renew after the term ends are usually much higher. Choosing the right term length is key.

Get a Term Life Insurance Quote → Full Term Life Insurance Guide →
Illustration representing Whole Life Insurance
Whole Life Insurance

Lifetime protection with guaranteed building blocks.

Whole life insurance is permanent coverage designed to last your entire life, as long as premiums are paid. It combines a death benefit with a cash-value account that grows at a rate set by the policy, giving your family long-term certainty.

Coverage lengthLifetime
Cash valueGuaranteed growth
PremiumsTypically fixed

How it works

  • Premiums are generally level and will not increase as you age.
  • A portion of each premium builds cash value, which grows tax-deferred at a guaranteed rate defined in the policy.
  • With some participating policies, the carrier may pay dividends, which are not guaranteed.
  • You may be able to borrow against the cash value; outstanding loans and interest reduce the death benefit.

Often a good fit for

  • People who want coverage that never expires
  • Families planning to leave an inheritance or legacy
  • Those wanting predictable, fixed premiums
  • Parents supporting a dependent who will need lifelong care
Things to consider

Whole life premiums are significantly higher than term for the same death benefit, and cash value may build slowly in the early years. Surrendering early can mean fees.

Get a Whole Life Insurance Quote → Full Whole Life Insurance Guide →

Illustration representing Universal Life Insurance
Universal Life Insurance

Permanent coverage that can adjust as life changes.

Universal life (UL) is permanent insurance with more flexibility than whole life. Within policy limits, you may be able to adjust how much you pay and how much coverage you carry as your income, family, and goals change over time.

Coverage lengthPermanent, if funded
Cash valueInterest-credited
PremiumsFlexible

How it works

  • Premiums go into a cash-value account; the cost of insurance and policy fees are deducted each month.
  • The cash value earns interest based on a rate set by the carrier, usually with a guaranteed minimum.
  • You may be able to pay more in good years and less in tighter years, as long as the cash value covers policy costs.
  • Some UL policies offer a "no-lapse guarantee" that keeps coverage in force if required premiums are paid.

Often a good fit for

  • People who want permanent coverage at a lower cost than whole life
  • Those whose income varies from year to year
  • Estate planning needs where coverage must last
  • People who want the option to change their death benefit later
Things to consider

Flexibility requires attention. Underfunding the policy, or lower-than-expected interest rates, can cause it to lapse. Reviewing your policy regularly is important.

Get a Universal Life Insurance Quote → Full Universal Life Insurance Guide →

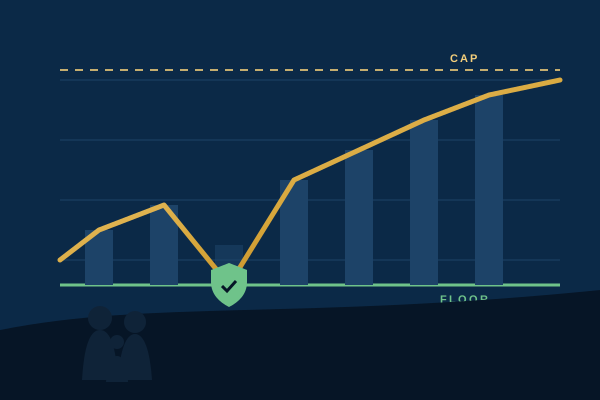
Illustration representing Indexed Universal Life (IUL)
Indexed Universal Life (IUL)

Growth potential with a built-in floor.

Indexed universal life is a type of universal life policy where cash-value interest is linked in part to the performance of a market index, such as the S&P 500®. Your money is not invested directly in the market, and policies typically include a floor that protects credited interest from going below a set rate — often 0%.

Coverage lengthPermanent, if funded
Cash valueIndex-linked
ProtectionFloor & cap

How it works

  • When the index rises, your cash value is credited interest up to a cap or participation rate set by the carrier.
  • When the index falls, the floor means credited interest does not go negative, though policy charges still apply.
  • Like other UL policies, premiums and death benefit may be adjusted within policy limits.
  • Cash value may be accessed through policy loans or withdrawals, which can reduce the death benefit.

Often a good fit for

  • People seeking permanent coverage with cash-value growth potential
  • Those comfortable with a more complex policy structure
  • Families building a long-term, supplemental financial strategy
  • Business owners exploring executive benefit planning
Things to consider

Caps, participation rates, and fees can change and limit returns. Illustrations are not guarantees. IUL policies need to be properly funded and reviewed regularly.

Get an Indexed Universal Life Quote → Full Indexed Universal Life Guide →

Illustration representing Final Expense Insurance
Final Expense Insurance

Help your loved ones say goodbye without the financial burden.

Final expense insurance is a smaller whole life policy — often in the range of a few thousand to tens of thousands of dollars — designed to help cover funeral costs, medical bills, and other end-of-life expenses so your family can focus on each other.

Coverage lengthLifetime
Coverage amountSmaller, targeted
UnderwritingSimplified

How it works

  • Applications are often simplified, with a short health questionnaire instead of a full medical exam.
  • Premiums are typically fixed and coverage does not expire as long as premiums are paid.
  • Some policies build modest cash value over time.
  • Guaranteed-issue options may be available for applicants with serious health conditions, often with a waiting period before the full benefit applies.

Often a good fit for

  • Seniors who want to spare their children funeral and burial costs
  • People who may not qualify for traditional coverage
  • Anyone wanting a simple, affordable permanent policy
  • Those who want to pre-plan and have peace of mind
Things to consider

The cost per dollar of coverage is higher than fully underwritten policies, and graded or guaranteed-issue policies may limit benefits in the first few years.

Get a Final Expense Insurance Quote → Full Final Expense Insurance Guide →

Illustration representing Mortgage Protection
Mortgage Protection

Keep your family in the home you built together.

Mortgage protection is life insurance planning focused on helping your family keep their home if something happens to you. Coverage is commonly structured with term or permanent life insurance sized to your mortgage balance — and unlike lender-issued mortgage insurance, the benefit is typically paid to your family, not the bank.

Coverage lengthMatches your loan
BeneficiaryYour family
OptionsTerm or permanent

How it works

  • Coverage is usually aligned with your mortgage amount and the years remaining on your loan.
  • Your beneficiaries receive the benefit and decide how to use it — pay off the mortgage, cover payments, or meet other needs.
  • Some policies include living-benefit riders that may help if you become critically or terminally ill, subject to terms.
  • Return-of-premium options may be available on some term policies for an additional cost.

Often a good fit for

  • New and existing homeowners
  • Families relying on two incomes to afford payments
  • Parents who want children to stay in the same home and schools
  • Anyone refinancing or buying a larger home
Things to consider

Mortgage protection is not the same as private mortgage insurance (PMI), which protects the lender. Make sure the coverage amount reflects your remaining balance and other family needs.

Get a Mortgage Protection Quote → Full Mortgage Protection Guide →

Side by Side

Compare your options.

A quick overview of how common life insurance types differ. Actual features depend on the carrier and policy.

TypeHow long it lastsCash valuePremiumsBest known for
Term LifeSet term (10–30 yrs)NoLevel for the termMost coverage for the lowest cost
Whole LifeLifetimeYes, guaranteed growthFixedCertainty and legacy planning
Universal LifePermanent, if fundedYes, interest-creditedFlexibleAdjustable permanent coverage
Indexed ULPermanent, if fundedYes, index-linked with floorFlexibleGrowth potential with downside protection
Final ExpenseLifetimeModestFixedSimple approval, end-of-life costs
Mortgage ProtectionMatches your loan (or longer)Depends on policyDepends on policyKeeping your family in their home
Choosing Coverage

What shapes the right policy?

$

Income & debts

Consider how many years of income your family would need, plus your mortgage, loans, and other obligations.

♥

Who depends on you

Children, a spouse or partner, aging parents, or a business partner can all shape how much coverage makes sense.

✓

Health & age

Premiums and eligibility are based on underwriting factors like age, health history, and lifestyle. Applying sooner often helps.

⏱

How long you need it

Temporary needs often fit term coverage, while lifelong goals may point toward permanent insurance.

⚖

Budget

The best policy is one you can comfortably keep. We help balance coverage with what fits your monthly budget.

★

Long-term goals

Legacy, estate planning, or cash-value features may matter to you — or they may not. Your priorities lead.

Questions

Common life insurance questions.

Can I have more than one life insurance policy?

Yes. Many people combine policies — for example, a term policy for years when children are young plus a smaller permanent policy for lifelong needs. This is sometimes called "laddering."

Do I need a medical exam?

It depends on the carrier, product, coverage amount, and your age and health. Some policies use simplified underwriting with only health questions, while others require a paramedical exam.

Can I convert my term policy to permanent coverage?

Many term policies include a conversion privilege that lets you switch to permanent coverage within a certain time frame without new medical underwriting. Terms vary by carrier.

Is the death benefit taxable?

Life insurance death benefits are generally received income-tax-free by beneficiaries, though there are exceptions. Please consult a tax professional for advice about your situation.

What happens if I miss a payment?

Most policies include a grace period, often around 30 days. If a premium isn't paid by the end of it, the policy may lapse. Permanent policies with cash value may use that value to cover premiums, depending on the policy.

Not sure where to start?

Let’s find the right fit together.

You don’t need to know which policy you want. Tell us about your family and goals, and we’ll compare options from multiple carriers.

Product availability, eligibility, underwriting, premiums, benefits, and policy terms vary by carrier, state, and individual circumstances. Cash value growth, dividends, and index crediting are subject to policy terms and are not guaranteed unless stated in the contract. Policy loans and withdrawals reduce cash value and death benefit. GMGSJ Insurance does not provide tax or legal advice. General information only; not an insurance contract or guarantee of coverage. S&P 500® is a registered trademark of Standard & Poor's Financial Services LLC.